The Horror of Modern Cars

kyleb

Final Approach
PoA Supporter
Joined
Jun 13, 2008
Messages
9,173
Location
Marietta, GA
Display Name
Drake the Outlaw
Home Airfield
Cartersville, GA
SWMBO got a new car this weekend. A Toyota Grand Highlander to be specific. She'd already worked out the deal and the financing before we went to the dealership on Saturday so it only took 3 hours (bash my head into the wall) to finish the deal. A fair portion of the time was consumed being pitched for the extended warranty. On one hand (the buying process)..."Toyotas are insanely reliable...last forever...top tier in all of the consumer reliability data." But once the topic turned to extended warranties "Modern cars are much more complicated than older vehicles. Just the big screen or inverter alone could cost you $5K in repairs and avoiding that would more than pay for the extended warranty." I think the price offered for the 10 year/100K mile warranty was $4K. After listening to the pitch for far too long I asked if the offer would be good tomorrow. "Yep." "OK, we're outta here."

A) I hate pressure sales.
B) If you can buy an extended warranty at about half of the initial asking price, it becomes a reasonable choice.
C) The complicated electronics thing is real. Even a windshield replacement on a modern car is stupid expensive because they not only have to replace the windshield but also have to recalibrate all the sensors, which can run a couple thousand bucks.
D) That used Miata I've been contemplating sounds better and better all the time due to its <relative> simplicity.
 
Last edited:
I just bought a new car and I was shocked how easy it was to tell them to shove all the extras they wanted to sell me right up their arse. They didn’t argue at all and 100% of my negotiating was done before ever stepping inside a dealership. I had the OTD price in an email and I didn’t pay $.01 more while picking it up.
 
I just bought a new car and I was shocked how easy it was to tell them to shove all the extras they wanted to sell me right up their arse. They didn’t argue at all and 100% of my negotiating was done before ever stepping inside a dealership. I had the OTD price in an email and I didn’t pay $.01 more while picking it up.
Same for SWMBO, but I was the wing-husband. It wasn't my duty to impolitely tell them to hand her the keys to the <paid for> car so we could leave. When she couldn't or wouldn't bring the endless back and forth about the warranty to an end, I had to play the ahole card.
 
You can't even replace the battery without it being a major programming event.
I'm going to dread that...I've been replacing batteries in all of the family vehicles forever...but nothing newer than 2016 so far, so never an issue.
 
Have a price in mind and call them beforehand. No negotiations and sales tactics when I bought my car. It was a very pleasant experience actually
 
SWMBO got a new car this weekend. A Toyota Grand Highlander to be specific. She'd already worked out the deal and the financing before we went to the dealership on Saturday so it only took 3 hours (bash my head into the wall) to finish the deal. A fair portion of the time was consumed being pitched for the extended warranty. On one hand (the buying process)..."Toyotas are insanely reliable...last forever...top tier in all of the consumer reliability data." But once the topic turned to extended warranties "Modern cars are much more complicated than older vehicles. Just the big screen or inverter alone could cost you $5K in repairs and avoiding that would more than pay for the extended warranty." I think the price offered for the 10 year/100K mile warranty was $4K. After listening to the pitch for far too long I asked if the offer would be good tomorrow. "Yep." "OK, we're outta here."

A) I hate pressure sales.
B) If you can buy an extended warranty at about half of the initial asking price, it becomes a reasonable choice.
C) The complicated electronics thing is real. Even a windshield replacement on a modern car is stupid expensive because they not only have to replace the windshield but also have to recalibrate all the sensors, which can run a couple thousand bucks.
D) That used Miata I've been contemplating sounds better and better all the time due to its <relative> simplicity.
if you can’t afford to buy the car without a loan and can’ afford to repair it unless you purchase an extended warranty you most likely will never use, you can’t afford a new car.
 
if you can’t afford to buy the car without a loan and can’ afford to repair it unless you purchase an extended warranty you most likely will never use, you can’t afford a new car.

He didn't say he couldn't afford to buy it without a loan - maybe he chose to buy it with a loan. Some new car loans offer 0%, 1% or 2% financing. If I have the choice of buying something for $50k in cash vs. financed at a rate lower than inflation and sure as hell lower than my yield with the money elsewhere, I'll choose financing every day and twice on Sundays!
 
Last two vehicles I purchased (both 1 year old used), the dealers did the same thing. This was after multiple emails nailing down the price. No I don't want paint protection. No I don't want extended warranty. No I don't want your discount service package (I live 700 miles from you). Finally get to closing time and travel to the place to get the car and they start in on the extended warranty. Tell them I'm not getting it. At one place the guy literally told me that I'll have to sign a paper stating that I'm refusing the extended warranty. Nope. Took me standing up and heading for the door and suddenly that wasn't required.
 
At one place the guy literally told me that I'll have to sign a paper stating that I'm refusing the extended warranty.
Last place I worked, some insurance guy convinced the GM that Federal Law required that employees attend an identity theft insurance sales meeting.

I didn’t believe that GM was as ignorant as he said he was until I worked with him for a couple of years. His favorite phrase to weasel out of issues was, “I wouldn’t know anything about that.” He was actually a ****ing idiot.
 
I will never go through the 'let me talk to my manager' thing again. Last one of those was 15 years ago and I walked out.

I figure out what vehicle I want, even if it's at a distance. I then email three dealers that have the vehicle for quotes and go with the best one. One I had shipped from Chicago, the other I drove to Atlanta to swap out with a trade. And CarMax is great for a high mileage used car sale that a new car dealer won't touch.

In my retirement years, I have found it easier to pay cash. When I started doing that I always had commitments from my credit union or USAA. Now I just send a money order or write a check.
 
Just remember, "No" is a complete sentence. When the finance manager starts on the whole extended warranty, service plan, etc., I cut them off immediately and just say "I'm not interested in any of that." When they push, just a flat "no" usually shuts them up. While that usually sours the mood when the finance guy starts pouting, I'm not going to waste my time being "polite" and let them explain all the ******** I already know I'm not buying. Say no and move on. If they start to pressure, just keep saying "no." Who cares if some finance manager thinks you're an a**hole?
 
You can't even replace the battery without it being a major programming event.
A good thing about Lexus, at least the ones I've owned from 2016 through 2023, is that no programming is required. AutoZone parking lot works fine. Swap out, drive off.
 
If you want a Toyota factory warranty just buy it after the vehicle. You can buy it up until the bumper to bumper warranty expires. Several dealerships around charge $100 over cost and it’s handled via email. Typically 20-40% the cost of buying it with the vehicle, and you can take your time reviewing the specifics. You can buy from any dealership in the US, and never have to see them.
 
Both of my last two car deals were completely handled ahead of time by text and email. The visits to the dealerships lasted less than 30 minutes to signs the papers and exchange the vehicles that were being traded in. The test drive was almost an after thought, as we were buying new and knew what we wanted.

I used to think extended warranties were a scam. However the cost of a 10yr/100,000 miles extended warranty on my truck was less than $2k. I knew I had spent well over $2k on my last truck on warrantable repairs in that same time frame. Sure enough the new truck required 4wd hub repairs (known issue on F-150 IWEs) just out of factory warranty, which more than made up the cost of the warranty already.

My wife's car we didn't do an extended warranty. The cost was too high and the available coverages were too low in my opinion. The thing I look at is the amount of coverage between the factory warranty and the extended warranty. If the factory is 3 yr/36k mile, and the extended is 5 yr/60k mile, you are only buying two years worth of coverage.
 
If you want a Toyota factory warranty just buy it after the vehicle. You can buy it up until the bumper to bumper warranty expires. Several dealerships around charge $100 over cost and it’s handled via email. Typically 20-40% the cost of buying it with the vehicle, and you can take your time reviewing the specifics. You can buy from any dealership in the US, and never have to see them.
The dealership we work with figured it out…they buy (build into the purchase price) a lifetime power train warranty for any car less than 10 years old with less than 100,000 miles. Probably a waste of money for most folks, but if they’d been doing it when we bought my wife’s car in 2016, she’d probably still be driving it. She really liked that car, but the current versions are crap.
 
He didn't say he couldn't afford to buy it without a loan - maybe he chose to buy it with a loan. Some new car loans offer 0%, 1% or 2% financing. If I have the choice of buying something for $50k in cash vs. financed at a rate lower than inflation and sure as hell lower than my yield with the money elsewhere, I'll choose financing every day and twice on Sundays!
Do you finance repairs that may or may not be required too? That’s what an extended warranty paid per month is. The smart new car buyer waits for cash incentives, not reduced interest rates.
 
Last edited:
I just bought a new car and I was shocked how easy it was to tell them to shove all the extras they wanted to sell me right up their arse. They didn’t argue at all and 100% of my negotiating was done before ever stepping inside a dealership. I had the OTD price in an email and I didn’t pay $.01 more while picking it up.
Depends on the dealership.

Watch some of this guy's videos. He negotiates car deals for consumers and records the process. While some dealerships have a straight-forward process, many others are still playing the games that have given them all a bad reputation.

 
Do you finance repairs that may or may not be required too? That’s what an extended warranty paid per month is. The smart new car buyer waits for cash incentives, not reduced interest rates.

I agree that extended warranties are pointless, hence I didn't even mention it in my response ;-) Still disagree with you on "smart car buyer waits for cash incentives, not reduced interest rates". Average cash incentive on a $50k car is somewhere between $5k and $10k. If I finance that same car at 0% for 5 years and keep the $50k invested, assuming a very modest 6% annual growth (inflation adjusted), I'll make over $15k in that timeframe. Sounds pretty smart to me to be honest, but we're all smart differently.
 
Depends on the dealership.

Watch some of this guy's videos. He negotiates car deals for consumers and records the process. While some dealerships have a straight-forward process, many others are still playing the games that have given them all a bad reputation.


Easy peasy.

Walk.
 
I agree that extended warranties are pointless, hence I didn't even mention it in my response ;-) Still disagree with you on "smart car buyer waits for cash incentives, not reduced interest rates". Average cash incentive on a $50k car is somewhere between $5k and $10k. If I finance that same car at 0% for 5 years and keep the $50k invested, assuming a very modest 6% annual growth (inflation adjusted), I'll make over $15k in that timeframe. Sounds pretty smart to me to be honest, but we're all smart differently.
How much of the loan incentive do you realize if you in 2 years if you die, sell the car before the end of the term of the loan, the car is stolen, destroyed in a natural disaster, or the car is totaled in a crash? The money is in your account after any of these events with a cash incentive or you may use a cash incentive to reduce the principle of the loan and retire the debt earlier.
 
Last edited:
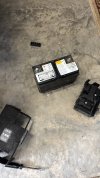
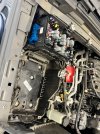
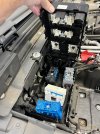
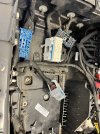
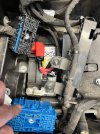
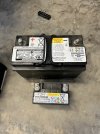
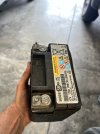
I just replaced the main and aux batteries on the ‘22 Wrangler. The main battery was easy, the aux battery was a big pain. Had to remove the main battery, then remove the fuse box/PDP, then remove four honkin electrical connectors, then remove the connector tray, move more wires, and then remove the lid to the aux battery box, and then finally fish the battery out of the hell hole where they buried it. Dealer wanted $400 labor plus the cost of batteries, and I said eff that and dove in.


3ADF3DE7-3ADD-46AC-B554-FAA591B27D58.jpegIMG_0370.jpegIMG_0371.jpegIMG_0372.jpegIMG_0373.jpegIMG_0376.jpegIMG_0375.jpeg
 
I agree that extended warranties are pointless, hence I didn't even mention it in my response ;-) Still disagree with you on "smart car buyer waits for cash incentives, not reduced interest rates". Average cash incentive on a $50k car is somewhere between $5k and $10k. If I finance that same car at 0% for 5 years and keep the $50k invested, assuming a very modest 6% annual growth (inflation adjusted), I'll make over $15k in that timeframe. Sounds pretty smart to me to be honest, but we're all smart differently.
Yep, same here. We don't turn over cars often and have never tried to buy one during a sellers market, so it's always been dealer financing at a low rate versus a cash incentive. Every single time it's been a much better deal to take the financing and keep the money invested somewhere.
 
I agree that extended warranties are pointless, hence I didn't even mention it in my response ;-) Still disagree with you on "smart car buyer waits for cash incentives, not reduced interest rates". Average cash incentive on a $50k car is somewhere between $5k and $10k. If I finance that same car at 0% for 5 years and keep the $50k invested, assuming a very modest 6% annual growth (inflation adjusted), I'll make over $15k in that timeframe. Sounds pretty smart to me to be honest, but we're all smart differently.
That $15k will even cover some of the depreciation on the $50k car. IMHO, the "smart car buyer" lets someone else take that hit. Buy that $50k car used for $35k, and never take the $15k out of your pocket.
 
So.....
1) Insurance is sold to make money for the seller. You are not going to come out money ahead by buying insurance. I you did, they wouldn't sell it to you at that price. Don't buy the extra insurance.

2) Agree - buy used and pay cash. BUT.... moot point. She has the car. So just pay that loan off as fast as possible to keep your upside down status as short as possible.

3) It's always OK to be something besides the wing husband. You, the guy, get to say "no" to the sales guy. and the wife (sometimes).... :biggrin:
 
1) Insurance is sold to make money for the seller. You are not going to come out money ahead by buying insurance. I you did, they wouldn't sell it to you at that price. Don't buy the extra insurance.
Isn't it the case that you're not trying to get ahead of the dealer but rather the pool of other people that also bought into it?

For example, you and 99 other people each buy $5k worth of extended warranty. 3 years and 1 day later you blow a $10k transmission. The other 99 transmissions continue to work just fine. You came out ahead. The dealer came out ahead. The 99 others are behind.
You can't even replace the battery without it being a major programming event.
My car stores the user settings in non-volatile memory.
Still disagree with you on "smart car buyer waits for cash incentives, not reduced interest rates". Average cash incentive on a $50k car is somewhere between $5k and $10k. If I finance that same car at 0% for 5 years and keep the $50k invested, assuming a very modest 6% annual growth (inflation adjusted), I'll make over $15k in that timeframe. Sounds pretty smart to me to be honest, but we're all smart differently.
Last time I was involved in the new-car buying process, factory financing was at a lower list price than cash. The obvious move was to take the loan and pay it off within the first month.
 
As far as the horror of modern cars, some modern cars are well designed, and many more are not.

Isn't it the case that you're not trying to get ahead of the dealer but rather the pool of other people that also bought into it?
Yeah, you're betting that you'll have more covered repairs than the cost of the warranty and the insurance company is better that you won't.

This goes back to the purpose of insurance. It is to pay for unexpected costs that you couldn't comfortably pay yourself. Odds are that you won't have more covered repairs than the cost of the insurance so, if you can afford the repairs, skip the insurance. Only 50%-60% of the cost of the insurance (warranty) is typically passed on to the insurance company.

Last time I was involved in the new-car buying process, factory financing was at a lower list price than cash. The obvious move was to take the loan and pay it off within the first month.
Manufacturer's often have incentives that pay the dealership a fee for signing customers up with their in-house financing. That will affect the discount that the dealership is willing to offer. You'll often be required to make a minimum number of payments before paying off the loan, but that might only be two or three payments.
 
Yeah, you're betting that you'll have more covered repairs than the cost of the warranty and the insurance company is better that you won't.
Right, but if the insurance company loses that bet then it's not the insurance company that lost money in the grand scheme of things. They aren't betting against you, an individual. They betting against the 100's of you that make up the customer base.
 
Right, but if the insurance company loses that bet then it's not the insurance company that lost money in the grand scheme of things. They aren't betting against you, an individual. They betting against the 100's of you that make up the customer base.
They're betting against all of there customers and they usually win more of those bets than they lose.
 
Seem to be saying that insurance is good because you think you’ll be the 1 in 1000 that will need it. The probability of a return on your investment on this insurance is close to nil.

And spot on with the other comment on zero interest car loan. There is no such thing as free. If you paid cash in this case you could have
gotten a lower price.
 
How much of the loan incentive do you realize if you in 2 years if you die, sell the car before the end of the term of the loan, the car is stolen, destroyed in a natural disaster, or the car is totaled in a crash? The money is in your account after any of these events with a cash incentive or you may use a cash incentive to reduce the principle of the loan and retire the debt earlier.

Those are a lot of If’s. What if Santa wasn’t real, we all would get nothing for Christmas.
 
Seem to be saying that insurance is good because you think you’ll be the 1 in 1000 that will need it. The probability of a return on your investment on this insurance is close to nil.
Insurance isn't an investment any more than betting on black at roulette is. Insurance is risk management.

Dealer extended warranties have a huge markup, but you can find deals. Then it's more like playing craps.
 
I don't think I've seen an aux battery in a regular passenger vehicle before, what's it's purpose?

Start/stop, and to assist adding capacity for all the extra electronic systems, lane assist, all the other crap. This is the second car I’ve owned with a second auxiliary battery, the first one was a 2006, so not a new concept.
 
Isn't it the case that you're not trying to get ahead of the dealer but rather the pool of other people that also bought into it?

For example, you and 99 other people each buy $5k worth of extended warranty. 3 years and 1 day later you blow a $10k transmission. The other 99 transmissions continue to work just fine. You came out ahead. The dealer came out ahead. The 99 others are behind.

My car stores the user settings in non-volatile memory.

Last time I was involved in the new-car buying process, factory financing was at a lower list price than cash. The obvious move was to take the loan and pay it off within the first month.
RE the reprogramming, it’s not for the settings. In the one I’m familiar with they designed a system that adapts to an aging battery by charging at a slower rate (or similar) to preserve the battery. However, when you put a new battery in, there is nothing to tell the battery management system to go back to “new battery” mode. Thus, without programming intervention, it undercharges the new battery to the point that the vehicle starts disabling features that pull current such as heated seats, etc.

At the end of the day, they could have easily allowed the system to self-reset. Dealers want desperately to force everyone to them for maintenance and this is one way.
 
Back
Top