Who covers your injuries in an airplane crash?

Salty

Touchdown! Greaser!
Joined
Dec 21, 2016
Messages
15,130
Location
FL
Display Name
Salty
Ok, so you own the plane, you are the pilot and you have an accident. Let's say it's due to a mechanical failure. You have a typical owners policy on your aircraft.

You and your passengers go to the ER to get checked out and perhaps get further medical treatment beyond that.

Which insurance kicks in first / later / whatever?

Will your regular medical cover this or will they deny and defer to your aviation specific insurance until those get maxed out?
 
Unless your regular medical policy excludes a specific activity - for instance, I made certain that my policy does not exclude any injuries I sustain as the PiC or passenger - they must legally cover you to the policy limits. Simple contract law.

I have belonged to several clubs. Each of which carried insurance on club aircraft. Those carriers must also cover any injuries sustained by persons operating or involved in covered club activities. (Meaning that breaking your ankle after falling in a gopher hole while wing running was covered.)

Insurance companies routinely subrogate claims AFTER payment to those covered who sustained a loss. This process should not under normal circumstances involve the injured party, and in no case should involve the injured party beyond making a sworn statement.

Disclaimer: unless you have paid me a retainer I am not your attorney and the proceeding is merely the opinion of SGOTI.

On a more upbeat note, the RASP shows lots of 2.5 to 3 m/s thermals nearby, wind under 15, and the NWS forecast is clear and 30 degrees for a high . . . that's 86 in 'Merican.
 
Which insurance kicks in first / later / whatever?
From what I've seen from the aircraft insurance side is your personal insurance or whatever kicks in first at the ER for several reasons, then, in general, your aircraft insurance merely reimburses those costs at a later date, if applicable.
 
Ok, so you own the plane, you are the pilot and you have an accident. Let's say it's due to a mechanical failure. You have a typical owners policy on your aircraft.

You and your passengers go to the ER to get checked out and perhaps get further medical treatment beyond that.

Which insurance kicks in first / later / whatever?

Will your regular medical cover this or will they deny and defer to your aviation specific insurance until those get maxed out?

Didn't you have to deal with some of this after your grove landing? Or didn't you use insurance for the medical stuff?

I'm not sure of the answer today, but back when I was racing I know my regular medical was supposed to be primary and my SCCA insurance was secondary. The SCCA policy was supposed to pick up any co-pays, as well as kick in after my primary insurance maxed out. I never needed it, though, so I can't say how well it all would have worked.
 
So who paid what?
Regular medical paid it all. I didn't try to recoup co-pays, perhaps I could have.

But I've recently read things in my policy that makes me surprised they didn't deny.
 
But I've recently read things in my policy that makes me surprised they didn't deny.

Interesting. I suggest not poking the bear.....

Possibly related - you might want to look over your policies, especially life, and make sure you're covered in the Chang. I know my life insurance policy with LockMart had an exclusion for military and experimental aircraft. When we needed to support flight tests, the company had to provide us with a special policy. Don't think it effected basic medical coverage, but it would have applied to life and disability.
Almost no policies cover when you are PIC of a GA aircraft.
 
Generally, health insurance pays first but may have a right of subrogation. Policy declarations for both health and airplane should address who’s primary payer and under what conditions.
 
I don’t believe the pilot is covered for medical by my policy. Occupants are.
 
Almost no policies cover when you are PIC of a GA aircraft.

There was no exclusion for that in our company policy. Just experimental and military.

We used to do some FLIR and radar testing using NG's BAC-111 testbed. https://photorecon.net/northrop-grummans-final-mission-in-the-bac-1-11/ We also used a Sabreliner as a flying testbed for some of the development of the Sniper pod. I was also involved with some testing using the Draken at the flight test center in Mojave. We flew Sniper on it, and also used it for some cruise missile launches. All those required special policies.

Now I did look at purchasing some extra life coverage (Mutual of Omaha, maybe?) one time, but there were so many exclusions it would have been useless. No coverage in the racecar, no coverage while scuba diving below 30', no coverage while cave diving at any depth, etc., etc.
 
When we needed to support flight tests, the company had to provide us with a special policy. Don't think it effected basic medical coverage, but it would have applied to life and disability.

My company has had to do this also. Was actually for flight tests on a LockMart aircraft. The company is protecting themselves, not the employee. Same as workers comp, disability, travel insurance, etc. If they don't provide generous coverage, that increases their exposure to liability suits in the event of employee injury or death, even if it is a military aircraft.

Work on the water is way worse than flying. We have a diving instructor who works with the SEALS. In addition to the usual coverages for medical, travel, life, STD, LTD, GL, and WC, we have to carry specific policies for longshoremen and commercial diving. We are literally paying more than his salary in insurance costs.

Right now I have at least 10 different insurance policies. It's crazy complicated to figure out the overlaps and gaps. As you get larger as a business, lawyers WILL test those gaps.
 
I don’t believe the pilot is covered for medical by my policy. Occupants are.

That is likely the case. In addition to aircraft loss, most policies cover liability in case the owner/operator is sued. If you crash, you are not going to sue yourself. But your passengers might sue you if they are hurt. Likewise for people and property on the ground.
 
Read your pilocies. Mine is clear. $100K medical for passengers per accident. Not per passenger, but in total. I can’t believe you guys don’t know what coverages you pay for.
 
Following our "event" the insurance company cut us a check for the add-on expenses, I believe it was 10k. My bride did not qualify for the $ medical for a passenger because she was listed as a co-owner. Lesson learned she is no longer a co-owner. Our personal medical coverage picked up everything else.
 
That is likely the case. In addition to aircraft loss, most policies cover liability in case the owner/operator is sued. If you crash, you are not going to sue yourself. But your passengers might sue you if they are hurt. Likewise for people and property on the ground.

Check the definitions in your policy. The entire definition of "passenger" in my policy reads

"Passenger" means a person while in, on, entering or getting out of the aircraft.​

That would seem to include the owner/pilot.
 
Read your pilocies. Mine is clear. $100K medical for passengers per accident. Not per passenger, but in total. I can’t believe you guys don’t know what coverages you pay for.
Given the number of questions we see about insurance whose only correct answer is, "what does the policy contract say," coupled with the number who give definitive answers as though they are universal, you should definitely be a believer.

I'm not an owner but I carry non-owned/CFI insurance. I actually switched companies this year because of a policy coverage item.
 
Check the definitions in your policy. The entire definition of "passenger" in my policy reads

"Passenger" means a person while in, on, entering or getting out of the aircraft.​

That would seem to include the owner/pilot.
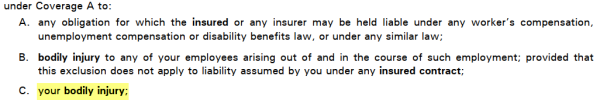
Maybe. You might find something in the Exclusions excluding... ("Coverage A" being the general bodily injury liability coverage)

1757003555960.png
 
Check the definitions in your policy. The entire definition of "passenger" in my policy reads

"Passenger" means a person while in, on, entering or getting out of the aircraft.​

That would seem to include the owner/pilot.

Ok, but what are your passengers covered for? My policy says liability. Elsewhere the policy defines liability as damages the insured becomes legally obligated to pay. Damages are defined as compensation from one party to another due to a wrongful act or failure of duty. I will leave it to the lawyers in the house to elaborate on whether I can owe damages to myself.

My policy does have a separate coverage for medical expenses including crew. But the limit of $5K is trivial.
 
Which insurance kicks in first / later / whatever?
The answer depends on the policy. Some aviation policies will say things like
1757005413283.png
Besides, coordination of benefits among a number of insurers can be complicated.

But there's a practical answer. You go into the ER. Staff asks for your insurance. Do you:
(a) Hand them your health insurance card;​
(b) Say, I have some insurance that may cover this but you'll have to wait until I go through the claims process.​

It's been several decades since I last handled one, but in the "typical" bodily injury case (aviation or not), health insurance comes into play first. If there is a third-party liability claim against you, the health carrier (and/or the medical provider) will be entitled to reimbursement from the proceeds. That's one of the reasons patients are asked about whether the medical problem was about an injury.
 
Back
Top