
eman1200
Touchdown! Greaser!
As a Millennial/Gen whatever comes after couple, @2-Bit Speed and I are literally living this in real time...as a one income household....
get a job, woman!
I kid I kid

As a Millennial/Gen whatever comes after couple, @2-Bit Speed and I are literally living this in real time...as a one income household....

I am not disagreeing that people should live within their means, I am pointing out that for many that is not an option.
get a job, woman!
I kid I kid
 Believe me, I'm working on getting a part time job, but due to other life ...stuff, it hasn't happened yet. The wonderful part about being a one-income household, though, is that all that part-time cash can go straight to whatever we're saving up for.

Don't strawman my position. I merely challenged your attempted flex about high interest rates in the past, in a conversation about present day buyers complaining about 7% rates. I retorted that 1992's rates were not the burden you imply they were, compared to today. That was my actual position and point.Knowing then what I know now, I'd have bought stock in Apple and Microsoft. I'd be a bazillionaire. I don't see how that's got anything to do with so-called "baby boomers" stealing your slice of the pie.


Don't strawman my position. I merely challenged your attempted flex about high interest rates in the past, in a conversation about present day buyers complaining about 7% rates. I retorted that 1992's rates were not the burden you imply they were, compared to today. That was my actual position and point.
Bringing up the interest rate of yesteryear is a common form of bad faith argument, because it purposely buries the lead, which is of course: The median income to median home price ratio of that time, compared to today's.
I’m going to go out on a limb here. I think many people choose for it not to be optional. FrEx, my daughter is a school teacher in Austin, so is her spouse. Both decided to buy their first house in the spring of 2022.I am not disagreeing that people should live within their means, I am pointing out that for many that is not an option.

My Dad was 42 before he thought he was well off enough to splurge on a car that had power windows, A/C, and holy cow, an FM radio (all cars before that had AM radios). We pleaded with him order the AM/FM/cassette stereo on that car, but he said nope, too much money. And besides, he said, who pays for music when it's free on the radio?
That's the mindset of an early boomer, very conservative with what they spent.

Wow, as a parent that had to be hard to watch.I’m going to go out on a limb here. I think many people choose for it not to be optional. FrEx, my daughter is a school teacher in Austin, so is her spouse. Both decided to buy their first house in the spring of 2022.
They both decided there was only three zip codes they would live, the house had to be from a particular flipper, and the house had to be originally built in the year they were born. They got exactly what they wanted with a zero down mortgage on a $418K selling price.
There were plenty of comparable new construction single family options at almost half the price in the zip code they were living in AND was closer to the schools each teach at. They also decided they both needed to start an M.Ed program, and that M.Ed had to be from a certain brand.
How two relatively new public school teachers are able to pay nearly $3900/mo on a mortgage is beyond me, but knowing their gross incomes (it’s public data) and existing debts, I can only assume they took student loans for the M.Eds and are using that to help pay their monthly bills, because both have publicly stated they do not have time for additional jobs, even in the summer.
I feel for them, their lifestyle is going to literally bankrupt them.


Interesting, the difference between what's looked for at large vs. small companies. I don't do hiring, but I'm often asked to look at the resumes of prospective engineering hires. Credentialism makes it hard to find that diamond in the rough. Some of the best engineers I've ever worked with had no degree at all.When I was hiring engineers for Lockheed, I often had a large stack of resumes and a short period of time to wade through them. ... I also toss the ones with GPAs < 3.0. Then I take the remaining ones and screen for relevant job experience, certifications, etc. Then with the remaining small stack I start reading in detail, looking for sweeteners like leadership experience, business training....
That's the reality. Maybe I missed an occasional diamond in the rough, but I hired a lot of great people who have been successful in the company.
"or" had a job. It was awfully tough to give engineering school the time it demanded while also working a job to offset a lot of the costs posted elsewhere in this thread. Okay I spent it on a Skywagon, but you get the point.When I look at resumes I ignore grades, yeah, the high GPA means smart and dedicated, but a lower GPA is often the really creative engineer who had fun in college.

One of the troubling things I've seen repeatedly in my life within my own family/friend circles is the bad financial decision makers living in a sort of financial denialism.I’m going to go out on a limb here. I think many people choose for it not to be optional. FrEx, my daughter is a school teacher in Austin, so is her spouse. Both decided to buy their first house in the spring of 2022.
They both decided there was only three zip codes they would live, the house had to be from a particular flipper, and the house had to be originally built in the year they were born. They got exactly what they wanted with a zero down mortgage on a $418K selling price.
There were plenty of comparable new construction single family options at almost half the price in the zip code they were living in AND was closer to the schools each teach at. They also decided they both needed to start an M.Ed program, and that M.Ed had to be from a certain brand.
How two relatively new public school teachers are able to pay nearly $3900/mo on a mortgage is beyond me, but knowing their gross incomes (it’s public data) and existing debts, I can only assume they took student loans for the M.Eds and are using that to help pay their monthly bills, because both have publicly stated they do not have time for additional jobs, even in the summer.
I feel for them, their lifestyle is going to literally bankrupt them.

Don't strawman my position. I merely challenged your attempted flex about high interest rates in the past, in a conversation about present day buyers complaining about 7% rates. I retorted that 1992's rates were not the burden you imply they were, compared to today. That was my actual position and point.
Bringing up the interest rate of yesteryear is a common form of bad faith argument, because it purposely buries the lead, which is of course: The median income to median home price ratio of that time, compared to today's.

But yes in general I've found the creative engineers have lower GPA's and are more able to think outside the box. High GPA engineers 'in general' are very good rule followers and test takers, but not necessarily the best engineers.
....but the small companies I've spent most of my career at need need the adaptable hands on types who are as comfortable in the shop joking with the mechanics while assembling the machine they designed as they are sitting in front of a tube designing it.
I’m going to go out on a limb here. I think many people choose for it not to be optional.

That doesn't even stand up to the most cursory examination. If that were the case, expanding population alone would have made everyone on Earth destitute.Actually, yes. There is only so much wealth that gets distributed. The myth of infinite economic growth is more ridiculous than santa claus or the tooth fairy.
I watch our kids and see both ends of the spectrum. One is debt free after several years of very disciplined fiscal behavior, and has decided they're not happy with paying the "outrageous" mortgage rates lenders are getting now, so instead of moving up to their next house now they'll just save up for a few years and pay cash unless the rates drop under 5% again.One of the troubling things I've seen repeatedly in my life within my own family/friend circles is the bad financial decision makers living in a sort of financial denialism.
The more in the financial hole they are, the less willing they are to sit down and add up the totals that they owe. A sort of financially perverse, reality avoidance technique.
Judgment comes from experience. Experience comes from bad judgment.Watching people drown themselves in debt, I've come to the conclusion that everything happens for a reason. Sometimes the reason is that they're idiots and make stupid decisions.


More than that. Here in the frozen north we get many well-heeled immigrants from the rapidly-industrializing Asian countries. They have the money to buy houses. Lots of houses. Prices shoot up and the local young people get squeezed out of the market.Those two things have combined to drive prices up significantly. Low supply caused by reduced production and growing population, high demand caused by low interest rates.
In 1980 we paid 15% on our $60K first house. A week after we signed the agreement to purchase we were offered $70K for it, but where would we have gone? All the affordable stuff was sold. Rates went to 22% after we bought, and many who took out one-year mortgages at 12% on the wishful thinking that the rates couldn't go any higher lost their places.The mortgage on our first house (1985-ish) was 13.5%, which was a bargain at the time.
Yup. Too many students sucked in by college advertising instead of examining the job market to see where the action is. So we have all sorts of social justice degrees, and no plumbers or electricians. Or aircraft mechanics.One interesting consideration is that millennials are much more likely to hold a college degree than boomers. But what fields did they study? How many of those majored in Mayan architecture or 14th century poetry? I really don't know, but some studies have shown that millennials took longer to land good jobs than boomers did. This might be indicative of a difference in job availability, and it might indicate a difference in job skills.
That there. When plumbers get scarce, they get expensive. I think I missed the coming aircraft mechanic shortage and the wages that will go with that.Too many kids were sold the "you gotta go to college and get a professional job or you're a failure"... when plumbers are making over $100 per hour. Oh yeah, and we're desperate for good experienced machinists and toolmakers, too.

What I have the biggest issue with is the concept of wealth "being distributed". It's not distributed. It's created and earned.

Wow, as a parent that had to be hard to watch.
That's interesting. My experience in finance (buy side) has been fairly opposite.One of the reasons I favored high GPAs when interviewing new grads is it gave me some indication of versatility. A person with a high overall GPA has done well in all of his classes, performing well with a variety of teachers, subjects, classmates / lab partners / project teams, etc., over a period of several years. I needed engineers that I could move to wherever they were needed, so I wanted to know that they could get along with different bosses and coworkers and succeed in a variety of assignments.
 (and thus expect to be comped as such, which leads to massive turnover in our industry)
The problem is these guys are good at repeating, not inventing. They're good at following instructions, not taking risks to do something a new way.

As a generation X'er its interesting to say the least watching fellow X'ers who didn't work as hard, invest as much or as early now falling into big inheritances from their boomer parents. While we end up working closer to 67 I know of several people still paying off houses, cars every 3 years, vacations - in debt - no savings. But in 2 years they will have a higher net worth than us and retire early (argghh!). Its been like this forever. But it seems the recent boomers are passing on a lot more wealth than any other generation both in number of families passing along significant wealth and level of wealth being passed on. Its like a weird equalizer for the X'ers in some regards.
Unfortunately the stats show the opposite. Boomers have one of the lowest savings rates in memory. As a group, their wealth is pretty much tied to the homes they live in, and not much else. At least, that is what my boomer parents tell me. I have read a few articles backing it up, but never really researched it.
Tim

The myth of finite wealth is more ridiculous than unicorns, as any quick review of human history will quickly illustrate.
In a world of finite resources, assuming anything is “infinite” is ridiculous.
In a world of finite resources, assuming anything is “infinite” is ridiculous.
The finite nature of this world must be why we're still murdering each with rocks, eating bugs, and not communicating at lightspeed across continents using devices our ancestors would call magic.
Wealth is created by applying ideas to resources.
For practical purposes, ideas are infinite and many resources for their implementations are renewable or reusable. The world is nowhere near the end of the wealth that can be created.
So technological development = infinity?
...all that part-time cash can go straight to whatever we're saving up for.

This is exactly the challenge millennials face that older generations don't seem to understand.
In the 70s/80s/90s, my dad could buy a basic truck. Now, a basic work truck is built to compete with a Cadillac. A single cab full size truck will often sell for $60k,
So technological development = infinity?
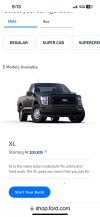
From Ford web site, 2-door basic pickup starts at $33.8k. Do dealers stock them? Nope, because people want fancy trucks. So much so that average Joes are willing to sign up for 72 and 84 month loans. Because, hey, I *deserve* to have a nice truck. That’s fricken nuts!
Fun point of reference for Ford trucks. I remember going with my father to look at new trucks in 1998, when the 1999s had just hit the lot. Sticker price for a new, loaded 1999 F-150 SuperCab Lariat was just over $22K. My father shook his head and said he'd never buy a truck for over $20K, despite having the means to do so. He found a used, loaded '98 Lariat that had 5K miles on it owned by the dealer for the past year and bought it for $18K, lol.View attachment 123013
From Ford web site, 2-door basic pickup starts at $33.8k. Do dealers stock them? Nope, because people want fancy trucks. So much so that average Joes are willing to sign up for 72 and 84 month loans. Because, hey, I *deserve* to have a nice truck. That’s fricken nuts!
Find a dealer that will let you order what you want. We bought a Jeep Wrangler last year, I wanted a basic 2-door stick shift bottom of the line model because it’s a fricken Jeep, not a luxury car. All the dealers stock are 4-door fancy pants mall crawlers that are $50k and up. So I ordered the base model, no sweat.

View attachment 123013
From Ford web site, 2-door basic pickup starts at $33.8k. Do dealers stock them? Nope, because people want fancy trucks. So much so that average Joes are willing to sign up for 72 and 84 month loans. Because, hey, I *deserve* to have a nice truck. That’s fricken nuts!
Find a dealer that will let you order what you want. We bought a Jeep Wrangler last year, I wanted a basic 2-door stick shift bottom of the line model because it’s a fricken Jeep, not a luxury car. All the dealers stock are 4-door fancy pants mall crawlers that are $50k and up. So I ordered the base model, no sweat.
That proves my point - it's 50k+.Not your locale, but a quick look at my closest Ford dealer shows a new white 250 2 door 8ft bed, 6.8 engine, 4wd, $50.5k. They’re out there, find a dealer that will work with you.
